

Mortgage Budget: Look Beyond Principal and Interest
A loan payment is only part of the cost of owning a home. Two properties with the same borrowed amount can have different monthly budgets because of taxes, insurance, building fees and maintenance. Use a calculator to compare scenarios, not as a lender's final offer.
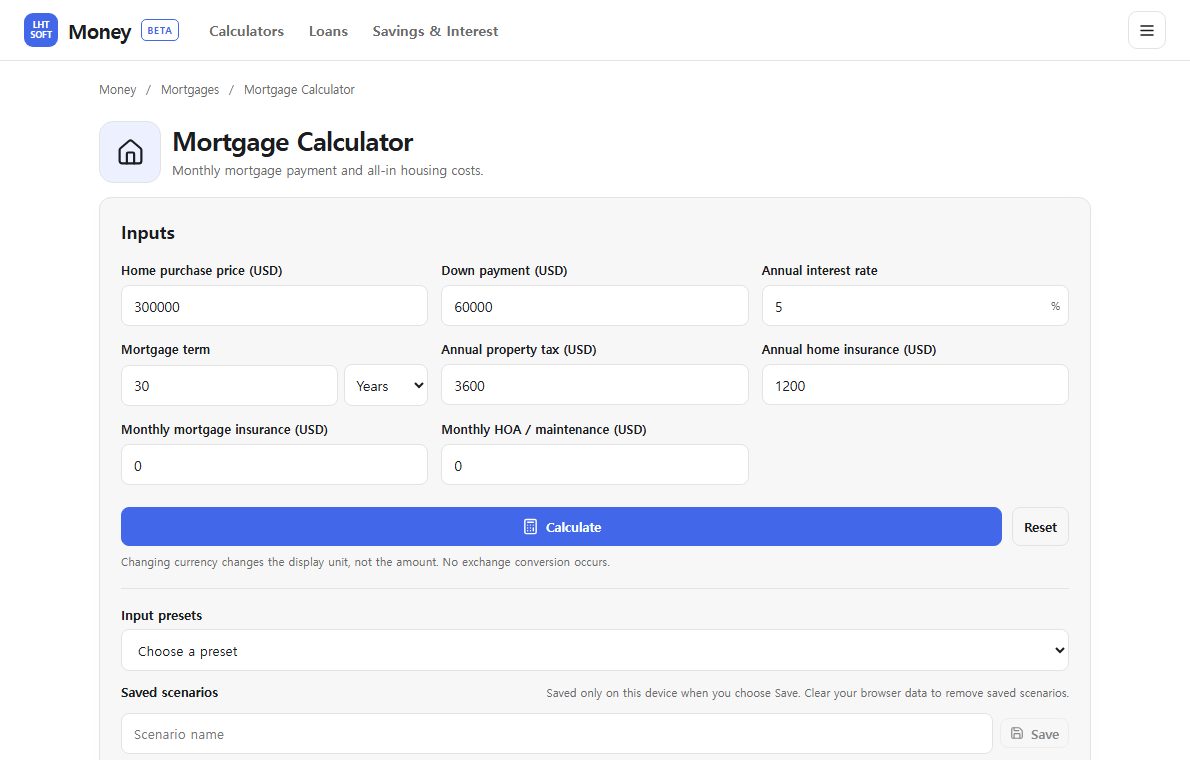
Start with loan terms
Enter the purchase price, down payment, rate and term. Distinguish the advertised rate from the actual offer and check whether the rate is fixed or can change. A longer term often reduces monthly principal and interest while increasing lifetime interest.
Add costs outside the loan
Include property tax, homeowner insurance, mortgage insurance where applicable and recurring association fees. Keep maintenance reserves and utilities in a separate household budget if the calculator does not include them.
Stress-test the assumptions
Compare a higher interest rate, a larger down payment and a different term. Try a scenario that includes unexpected repairs. The goal is to see whether the payment remains comfortable, not simply whether the maximum amount is technically affordable.
Compare total cost and cash reserves
Review initial closing costs and cash left after down payment. A low monthly payment with very little emergency savings can still be fragile. Write down which inputs came from real quotes and which are estimates.