

Loan payment, early payoff or refinance: which calculation first?
A single monthly payment does not tell the whole borrowing story. The useful calculation depends on whether you are taking a new loan, paying extra on an existing loan or considering a replacement loan.
Estimating a new loan
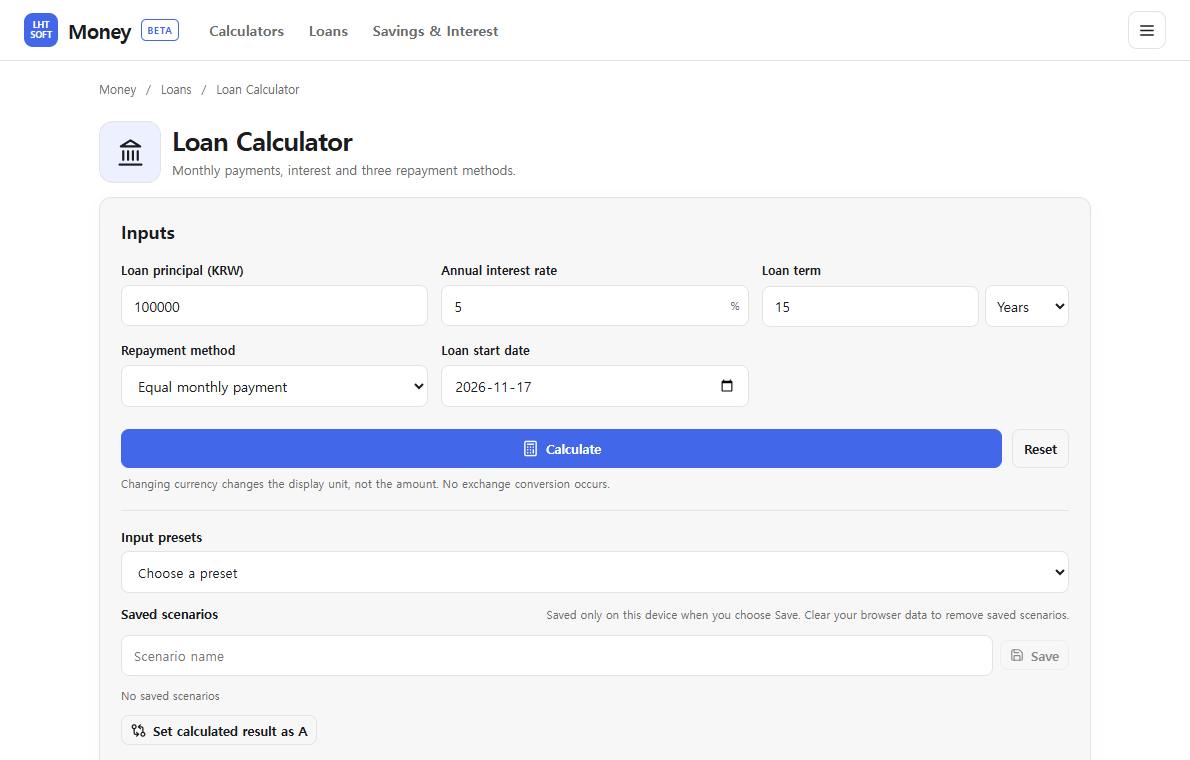
Start with the loan calculator to compare principal, interest rate, term and monthly payment. Look at total interest as well as monthly affordability. For a mortgage, account separately for taxes and insurance when applicable.
Paying extra on an existing loan
Use early payoff to estimate how an additional monthly or lump-sum payment changes the repayment period and interest. The outcome depends on lender rules, timing and any prepayment fee.
Replacing one loan with another
Use refinance to compare the remaining loan with a new rate, new term and fees. A lower monthly payment can come from a longer term and still increase total borrowing cost, so compare total cost and break-even timing.